Everything about Pix: 74 terms explained, from the key to MED
Pix key, txid, EndToEndId, MED, precautionary block, automatic Pix. A reference page covering 74 Pix terms in a few lines each, with a section on the terms a literal translation ruins.
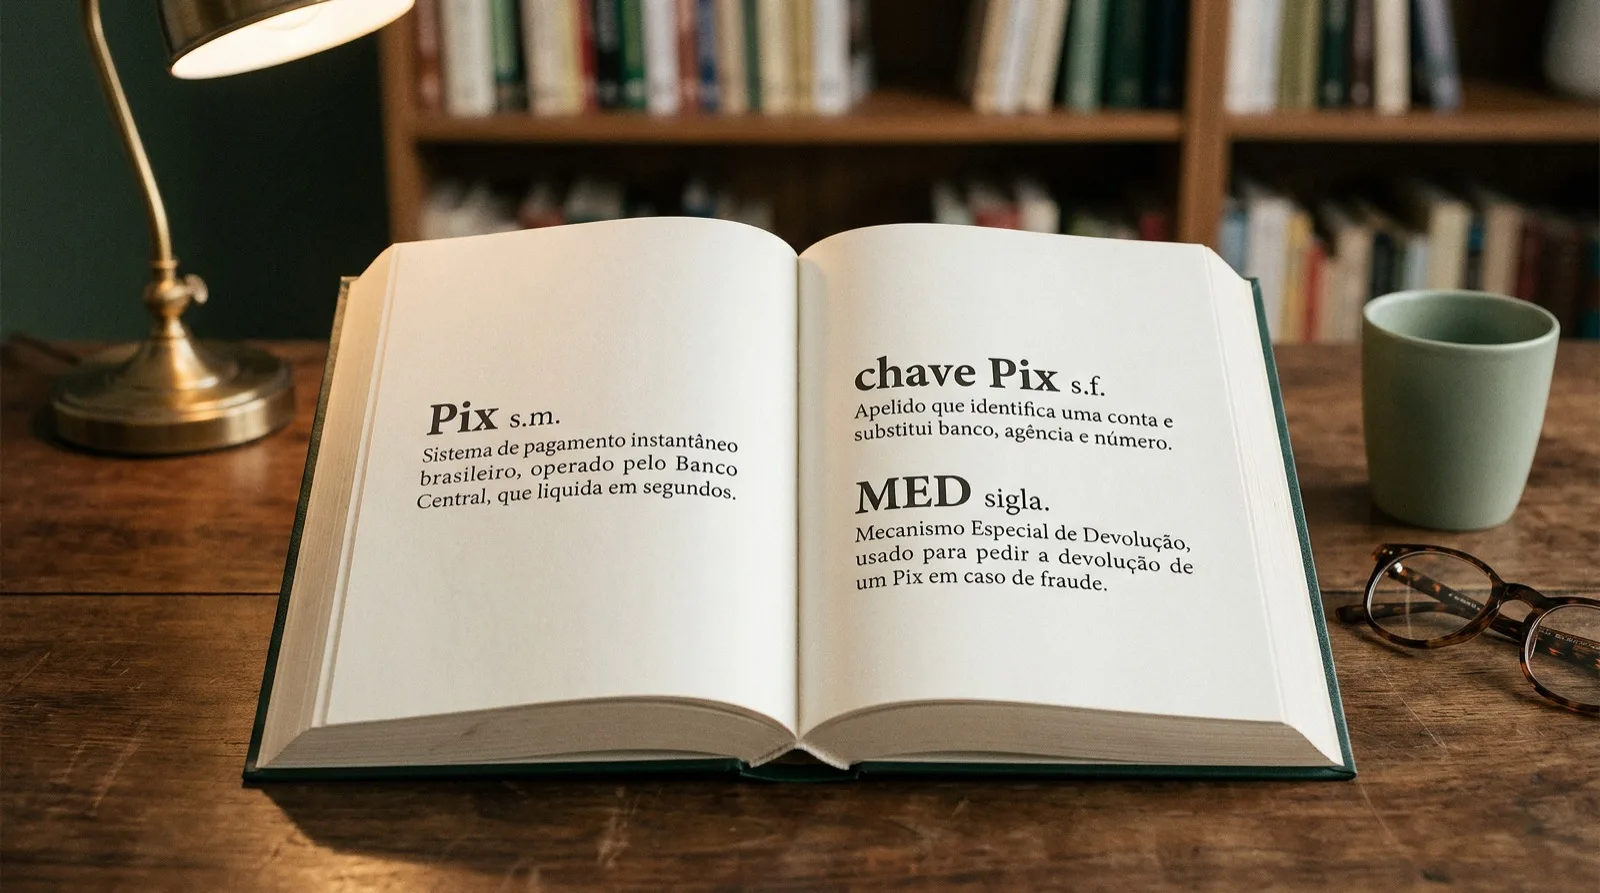
This page sets out the vocabulary of Pix, Brazil’s instant payment system, one term at a time: key, QR code, EndToEndId, txid, MED, precautionary block, automatic Pix and the rest. Each definition is short enough to read on its own and long enough to say what the term means in practice. A dedicated section covers the terms that have a false equivalent abroad, where a literal translation leads a contract in the wrong direction.
Pix launched in November 2020 as a transfer system. Six years on, it is a payment scheme with modalities, identifiers, regulatory deadlines, a refund mechanism and a roadmap of its own. The vocabulary followed. Terms like txid, EndToEndId, precautionary block and indirect participant used to live in technical documentation. They now show up in contracts, in month-end meetings and in dispute emails.
That leaves two kinds of reader stuck. Inside Brazil, the company that receives an MED notice about a payment taken three weeks ago and finds explanations written for the defrauded consumer, not for the business that sold something. Outside Brazil, the company that reads in a contract that a supplier will be paid “by Pix key”, knows bank transfers and IBANs, and finds no exact equivalent for what it just read.
This page answers both at once.
How to use this page
Every term is written to be read alone, without depending on the one above it. Use your browser’s search to find the acronym you need, or read a whole section when the goal is to understand a territory.
The order is not alphabetical, it is the order in which the terms show up in real life. First what Pix is and who runs it. Then how an account is found, how a charge is created, what the modalities are, what happens when something goes wrong, how limits and controls work, and how Pix enters a company’s back office. The section for readers outside Brazil comes last, with the terms a literal translation ruins.
What Pix is and who operates it
Before the vocabulary of charging and refunding, it helps to fix what Pix is as infrastructure. Most of the confusion about timing, cost and reversal comes from treating Pix as a bank product, when it is a system operated by the country’s central bank.
According to the Pix Management Report published by the Central Bank of Brazil in August 2026, the system processed around 79.8 billion transactions in 2025. That volume is why this vocabulary became routine.
Pix
Brazil’s instant payment system, created and operated by the Central Bank of Brazil, live since November 2020. It settles transfers in seconds, 24 hours a day, seven days a week, holidays included. It is not an app and not one institution’s product: it is public infrastructure that institutions connect to and offer inside their own channels.
Payment scheme (arranjo de pagamento)
The set of rules defining how a payment instrument works: who may participate, what the obligations are, how money settles and what happens when something fails. Pix is a scheme instituted by the Central Bank, which is why its rules are identical across every participating institution, with no bilateral negotiation.
Pix Regulation (Regulamento do Pix)
The Central Bank document that details how the scheme works, updated frequently. It holds the deadlines, each participant’s obligations and the refund rules. When an institution announces “a change to Pix”, it is almost always reflecting a change to this document rather than a decision of its own.
SPI (instant payment system)
The infrastructure operated by the Central Bank where Pix transactions actually settle, one by one, in real time, in accounts held at the central bank itself. This is what makes settlement final within seconds: there is no netting cycle and no cut-off window. SPI moves the money; DICT only says where it goes.
DICT (directory of transactional account identifiers)
The central registry, maintained by the Central Bank, linking each Pix key to its account and account holder. When a payer types a key and sees the recipient’s name before confirming, that name came from DICT. It is also the registry consulted when a key is ported or claimed.
Pix participant (PSP)
An institution authorised to offer Pix to customers, whether a bank, a payment institution or a credit union. Since 2025, access to the scheme has been restricted to institutions authorised by the Central Bank, which changed the profile of who can connect to the system.
Direct and indirect participant
A direct participant connects to SPI itself and settles its own transactions. An indirect participant reaches the system through a direct participant that settles for it. The end-customer experience is identical, but the distinction matters in contracts and in risk reviews, because it defines who is operationally answerable for each step.
Real-time settlement
A model in which each transaction settles individually, at the moment it happens, with no netting window. It is the opposite of the batch model used in traditional transfers and in cards. In practice, money credited is already available, with no further wait to “become balance”.
Irrevocability
The property by which a settled Pix is not automatically undone and cannot be cancelled by the payer. Any return of funds happens as a new operation: either a refund issued by the recipient, or an MED request analysed by the institutions. This is the structural difference from a card, where a chargeback reverses the original transaction.
Pix Forum
The working body coordinated by the Central Bank where scheme participants discuss how the system evolves, with working groups and a delivery calendar. It is the most reliable source on what is coming, and also the reason press announcements about “new Pix features” often arrive before any rule is published.
Pix keys and addressing: how an account is found
This is the layer that causes the most contractual confusion, because it replaces traditional bank identification with a nickname that can change owner, institution and format.
Pix key (chave Pix)
A nickname identifying an account, replacing bank, branch and account number. It can be a CPF (individual tax ID), a CNPJ (company tax ID), an email address, a phone number or a system-generated random key. An account can hold more than one key, and each key belongs to a single account at a time. The key is not the account: it is a pointer to it, and that pointer can be moved.
Random key (EVP)
A system-generated string with no relation to the holder’s document, email or phone. It is what a company uses when it does not want to expose its tax ID or email on a public charge, and when it wants distinct keys for distinct purposes. EVP is the technical abbreviation that appears in documentation and integration screens.
Key portability
The process of moving an existing key from one institution to another while keeping the same address. Anyone already paying that key keeps paying it, with no record to update. It is the mechanism that lets a company change banks without reissuing charges or notifying its customer base.
Ownership claim (reivindicação de posse)
The process by which someone requests a key currently registered to another account, proving the identifier belongs to them, as when a phone number changes hands. The institution holding the key has a deadline to respond, and silence transfers the key. Companies should monitor this: a claimed key that goes uncontested stops working.
Holder verification
Displaying the destination account holder’s name before the payment is confirmed, based on DICT data. It is the main defence against a typo and against a key swapped on a forged invoice. In high-volume payment operations, checking that name against the supplier record is a cheap and effective control.
Pix by bank details
Paying by entering bank, branch, account and the holder’s tax ID, without using a key. It settles identically and serves payers whose counterparty has no key registered, or one-off payments to third parties. It is the route used when a supplier prefers not to expose a public identifier.
Manual Pix
Informal term for a payment typed on the spot, as opposed to one read from a QR code or generated by an integration. It is where errors in amount and recipient concentrate, which is why high-volume operations move to dynamic QR codes or to batch files.
Key limit per account
The cap on how many keys one account may hold, set by the Pix Regulation and different for individuals and companies. For companies the number is higher, precisely because splitting keys by unit, product or purpose helps identify incoming money.
Charging over Pix: QR codes, copy-and-paste and identifiers
This vocabulary decides whether reconciliation will be automatic or manual. The difference between receiving an identified Pix and an anonymous one is entirely a choice of charge format.
BR Code
The Brazilian payment code standard, defined by the Central Bank, that underpins the Pix QR code. It specifies which fields exist and in what order, which is why any app from any institution can read any Pix QR code, with no prior agreement between the parties.
Static QR code
A fixed code that can be printed and reused indefinitely. It usually carries no amount, or always the same amount, and does not identify who paid. It handles simple situations but obstructs reconciliation as volume grows, because identical payments arrive and the team has to deduce the origin of each one.
Dynamic QR code
A code generated once per charge, carrying its own amount, due date and identifier. It is the format that lets a company know exactly which invoice was paid without asking the customer. At volume, the difference between static and dynamic is the difference between guessing and knowing.
Pix Copia e Cola (copy-and-paste Pix)
The text version of a QR code, used when scanning an image is impractical, as in an email, a PDF or a chat. It carries exactly the same information as the equivalent QR code, including the charge identifier. It is the most common format in business-to-business billing, because it travels well through any channel.
Pix Cobrança (structured charge)
The modality in which a company issues a structured charge, with amount, due date and debtor details, instead of simply receiving a transfer. It supports interest, late fees and early-payment discounts. It is Pix taking the place that only the boleto used to occupy, a comparison covered in Dynamic boleto and payment by Pix.
Immediate charge and charge with due date
The two types of Pix Cobrança. The immediate one is for payment on the spot, with no future date. The one with a due date supports interest, late fees and early-payment discounts. Technical documentation calls them cob and cobv, and the choice between them defines what the system can charge after the due date.
txid
The charge identifier, set by whoever issues the charge. It is the field where a company writes its order, invoice or contract number so the payment comes back already linked to its origin. Issuing charges with an empty txid means giving up automatic reconciliation and handing the work back to a person.
End-to-end identifier (EndToEndId)
The unique code that travels with each Pix transaction from start to finish, assigned by the payer’s institution. It is the number that traces a specific payment between institutions and the field that underpins any investigation of a discrepancy, refund or dispute. Where txid describes the charge, EndToEndId describes the transaction.
Interest, late fees and discounts
Amounts that can be applied automatically to a charge with a due date, depending on when it is paid. The calculation happens at payment time, against rules written into the charge itself. It is what allows a company to replace boletos with Pix without losing the collection policy it already had.
Payment receipt (comprovante)
The document an institution generates recording a transaction, with amount, date, the parties and the end-to-end identifier. It works as proof of payment, but an image of one is trivially forged, so it should never replace checking the statement. A receipt sent over a messaging app is a notice, not a confirmation.
Pix modalities: the ways to pay and to charge
Pix stopped being one single thing. Each modality below has its own rules on who authorises, when the money leaves and what happens if the balance is short.
Pix Transferência (transfer)
The original and most used modality: sending value directly from one account to another, settling in seconds. It is what most people mean by “sending a Pix”, and it is the conceptual base for every other modality.
Scheduled Pix (Pix Agendado)
A transaction the payer schedules for a future date. The money leaves on that date if there is balance; if there is not, it fails. It is a unilateral decision by the payer, not an agreement with the recipient, and that is what separates it from automatic Pix.
Automatic Pix (Pix Automático)
The modality in which a customer authorises once and the company then charges on a recurring basis, with no new action each cycle. Available since June 2025, designed for periodic billing such as tuition, subscriptions and continuing services. It works at any participating institution, with no bilateral agreement. Trio covers how it works in Automatic Pix: what it is and how it works and its effect on collections in How automatic Pix can transform receivables management.
Recurring Pix
A broader term for any repeated billing arrangement over Pix, including those that predate automatic Pix and relied on the customer paying actively each cycle. Recurring Pix covers where one model replaces the other and where both still coexist.
Automatic Pix authorisation
The consent a customer gives once, inside their own institution’s app, allowing a company to charge in the cycles that follow. It can carry a value cap and can be cancelled by the customer at any time. For the company, tracking the status of these authorisations matters as much as tracking the payments.
Batch Pix
Sending many Pix transactions in a single command, from a file or an integration, rather than one at a time on screen. It is the format used by companies paying hundreds of suppliers or making daily payouts, and it cuts both time and keying errors. Trio covers it in Batch payments.
Contactless Pix
Paying by tapping a phone against a terminal, with the same gesture as a contactless card. Available since February 2025. It changes the experience at the point of sale, not the nature of the transaction: it is still Pix, settled in seconds and credited straight to the account, with no settlement delay.
Pix Saque and Pix Troco (cash out and cash back)
Modalities where a customer receives physical cash from a merchant and the amount is debited by Pix. Pix Saque is cash withdrawal alone; Pix Troco attaches it to a purchase. Of little relevance to business-to-business payments, but common in retail.
Instalment Pix (Pix parcelado)
A product offered by institutions in which the payer splits the amount into instalments while the recipient is still paid in full upfront. It is not a modality of the Pix scheme: it is credit, with interest and terms set by each institution. As of November 2026 the Central Bank had published no specific rule standardising it, which makes comparing offers entirely the buyer’s responsibility.
Guaranteed Pix (Pix Garantido)
A feature announced by the Central Bank in 2025, with no launch date as of November 2026, intended to allow future Pix receivables to be pledged as collateral in credit operations. The stated goal is cheaper credit for smaller companies. Until it exists, what is available are advance-payment products offered by institutions under their own terms.
International Pix
The term used for the possibility of connecting Pix to instant payment systems in other countries. As of November 2026 it was under study at the Central Bank, with no published timeline. A company that needs to receive from abroad today still depends on foreign exchange and existing cross-border arrangements, not on Pix.
When something goes wrong: refunds, MED and fraud
This is the section that matters most to sellers, and the one most often read too late. The deadlines here are short and they run against the recipient.
Pix refund (devolução)
An operation in which the recipient returns the amount, in full or in part, on their own initiative. It differs from an automatic reversal: it depends on the recipient’s willingness and balance, and it links back to the original transaction through the end-to-end identifier. For most commercial situations, it is the correct and fastest route.
MED (special refund mechanism)
A set of Central Bank rules, in force since November 2021, allowing a refund request on a Pix in cases of fraud, scam or operational failure by an institution. It is not an automatic reversal: the payer’s and the recipient’s institutions analyse the case, block the amount if there is balance, and decide on the refund. How MED works explains the flow from the recipient’s side.
MED 2.0
The informal name for the overhaul set out in a Central Bank resolution published in August 2025 and effective from February 2026. It widened the mechanism in three ways: a claim can now be opened in the customer’s own app without speaking to anyone; tracing follows the money beyond the first destination account; and a refund can reach funds held in other accounts of the same holder.
Precautionary block (bloqueio cautelar)
A temporary hold on the amount in the destination account while an MED request is analysed. It reaches available balance, which is why the speed of the claim changes the outcome: money already moved on is harder to recover. For a recipient acting in good faith, it shows up as an unavailable amount on the statement, with no immediate explanation.
MED contest (contestação)
The response from a recipient who took a legitimate Pix and had the amount refunded wrongly. The window went from 30 to 80 days, counted from the refund date, under a Central Bank rule in force since September 2026. For a seller, that window is the difference between absorbing the loss and recovering the sale.
Self-service claims
The requirement that a refund claim can be opened by the customer inside their own app, without going through a call centre. In force since February 2026. The practical effect is that claims arrive faster, which raises the chance that there is still a balance to block and shortens the recipient’s time to respond.
Infraction report (notificação de infração)
A record filed by an institution to flag an account or transaction as suspected fraud. It feeds the risk databases other institutions consult and is usually the first step before a refund request. An account with accumulated reports meets more friction across the whole system, not only at the institution that filed.
Commercial dispute (desacordo comercial)
A situation where goods never arrived, a service was not delivered or quality fell short. It is not grounds for MED, and this is one of the most common misreadings among sellers: the mechanism covers fraud and operational error, not dissatisfaction with a purchase. The route in these cases is a negotiated refund.
Fake receipt scam
A fraud in which a buyer presents an image of a Pix receipt that never settled, or that went to a different account, and takes the goods before anyone checks. It is why confirming the credit on the statement, rather than the image received, is a cash control and not excessive caution.
Suspicious transaction
A classification an institution applies to a payment showing signs of fraud, which can delay release, trigger a request for further information or lead to a block. Companies receiving high or atypical amounts should know this review exists and that documentation of the sale is what clears it fastest.
Limits, hours and controls
Pix runs 24 hours a day, but not at the same limit at every hour. These are the terms that surface when a large payment stalls at 5pm.
Pix limit
The cap each institution sets per transaction and per period, based on profile, history and channel. For companies the limit is usually adjustable on request. Reviewing it before a significant payment avoids discovering the ceiling at the moment the money needs to move.
Night-time limit
A reduced cap applying during night hours, set by the Pix Regulation as a safety measure against coercion and express kidnapping. It applies to individuals and can be adjusted within specific rules. Operations that pay outside business hours need to account for it when planning their routine.
Limit increase request
A request to raise an account’s ceiling, which may carry a review period and an effective date rather than applying immediately. The operational point is simple: the increase is not instant, so the request has to precede the need rather than accompany it.
Registered device
A device the institution recognises as trusted for a given user. Payments from a new device usually face lower limits and extra verification. In companies that change equipment or staff often, this explains a good share of the refusals that look random.
Approval rights (alçada)
The rule defining who may approve a payment and up to what amount before it is sent. It is not a mechanism of the Pix scheme, it is a company’s control over its own account, and in Trio’s panel it appears as an approval rule. It is the control that separates whoever keys a payment from whoever authorises it.
Transactional account
An account used to move funds and settle payments, whether a current account, a payment account or a savings account. The term appears in Pix vocabulary because this is what a key is bound to. The account type matters when the subject is fund segregation and the profile of the institution.
Pix inside a company’s operation: integration and reconciliation
For a company, Pix does not end when the money arrives. It ends when the amount received has been explained, linked to an order and recorded. These are the terms of that stage.
Pix API
The technical interface through which a company’s systems create charges, query payments and send money without going through the bank’s screen. It is what lets an ERP issue a charge with the order identifier already filled in. Trio covers integration and payment experience in Product flows, SDK and Open Finance.
Webhook
An automatic notice the institution sends to the company’s system the moment a payment happens, instead of the company polling for it. It is what makes it possible to release an order seconds after a Pix confirms, with no human step.
Digital certificate and mTLS
The authentication mechanism used in Pix integrations, where both ends of the connection prove who they are by certificate. In practice, it is what stops a third party impersonating the company’s system. The thing to watch is expiry: a lapsed certificate takes the whole integration down, usually on the worst possible day.
External ID
The field where a company writes its own identifier on a charge or payment so it can find it again on the statement. It is the name used in Trio’s panel for what Pix documentation calls txid. Without it, reconciliation falls back on amount and date, which is exactly where it fails.
Reconciliation by identifier
The practice of matching statement lines to internal records using a code that travels with the transaction, instead of amount, date and name. It is what closes most incoming payments automatically and leaves only the remainder for human review. The record-keeping routine behind it is covered in Document management.
Pix statement
The record of account transactions with the scheme’s own fields, including the end-to-end identifier, the key used and the parties’ details. It is the authoritative source for confirming a payment, ranking above any receipt a customer sends, and it is the input to automatic reconciliation.
Same-day settlement
Funds available the same day the sale happens, with no settlement delay. It is Pix’s default behaviour, and the contrast with cards and boletos is what most changes cash predictability for a seller. The whole receivables-advance market exists because other instruments do not behave this way, as covered in Receivables advance and supply chain finance.
Pix fees for companies
What an institution charges a business for receiving by Pix, freely set by each one. For individuals, the scheme’s rules bar charging in most cases; for companies, they do not. That is why comparing Pix costs across institutions is worthwhile, and comparing Pix costs against card costs even more so.
Split over Pix
Automatically dividing an incoming payment among several recipients at settlement, used by marketplaces and platforms. It is an arrangement built on top of Pix by the institution, not a feature of the scheme, and it should not be confused with the tax split payment of Brazil’s tax reform.
Virtual account
A subaccount tied to a main account, used to separate incoming funds by customer, unit or purpose. Each can carry its own key or identifier, which solves payer identification without requiring a dynamic QR code. Its use in payouts is covered in Wallets for affiliates and virtual accounts.
Refund reconciliation
The routine of tying each refund back to the original payment and to a reason, so cash records do not keep an inflow that has already left. It is the most neglected part of the process, and the one that produces month-end discrepancies when an MED refund surfaces weeks after the payment.
Terms a literal translation ruins
These are the Pix terms with an apparent equivalent in other markets, where the appearance is exactly what causes the error.
Pix is not merely an “instant payment”. It is a system operated by the central bank, mandatory for institutions above a certain size, settling finally in seconds at any hour, at zero cost to individuals in most cases. The right comparison is to public payment infrastructure, not to a market product like Zelle or a card scheme.
A Pix key is not an IBAN. An IBAN identifies an account permanently, under an international standard. A Pix key is a nickname pointing at an account, which can be changed, ported to another institution and set as an email address or a phone number. Contractually, that means a key is not a stable account identifier and should not be treated as one.
Pix is not a digital wallet. There is no balance inside Pix. The money sits in a bank or payment account, and Pix is the rail that moves it. Anyone thinking of Pix as PayPal or Venmo is expecting an intermediary account that does not exist.
An invoice is not a boleto, and neither of them is a Pix. The invoice is the commercial document. The boleto is a payment instrument with a code any institution recognises. Pix is the system that settles. A Brazilian supplier may issue an invoice, hand over a copy-and-paste Pix string and never produce a boleto, and the three concepts stay distinct.
MED is not a chargeback. Chargebacks belong to the card world, are run by the schemes and also cover dissatisfaction with a purchase. MED is a central bank mechanism applying to Pix, covering fraud and operational failure, blocking available balance and decided by the institutions involved. Anyone selling into Brazil should learn it before needing it.
Pix has no acquirer and no MDR. There is no scheme, acquirer or interchange in the chain. An institution may charge a business for receiving, but that is its own commercial price, not a scheme fee. This changes the economics of accepting payment in Brazil and is one reason Pix spread through commerce so quickly.
Pix is not reversible. There is no payer cancellation and no chargeback window. Money comes back only through a refund issued by the recipient or a decision on an MED request. Contracts drafted on the assumption of card-style reversibility describe behaviour that does not exist here.
A CNPJ is not merely a tax ID. It is the legal entity identifier used to open accounts, issue invoices, receive payments, register collateral and register a Pix key. Brazilian groups commonly operate several CNPJs, which is why consolidating cash in Brazil takes more work than it does under a single-account structure.
Pix terms that look alike and are not
Six pairs account for most misreadings in contracts and in meetings.
| Term | Not to be confused with | The difference in one line |
|---|---|---|
| Automatic Pix | Scheduled Pix | In automatic Pix the customer authorises once and the company charges in later cycles; in scheduled Pix the payer programmes each transaction |
| MED | Pix refund | MED is a claim analysed by the institutions; a refund is issued by the recipient on their own initiative |
| MED | Chargeback | MED belongs to Pix and covers fraud or operational error; a chargeback belongs to cards and also covers purchase disputes |
| txid | EndToEndId | txid identifies the charge and is set by the issuer; EndToEndId identifies the transaction and is assigned by the payer’s institution |
| Dynamic QR code | Static QR code | The dynamic one belongs to a specific charge and carries an identifier; the static one repeats and cannot tell payers apart |
| Split over Pix | Split payment (tax) | The first divides a sale’s value among recipients; the second separates the tax and sends it to the tax authority at settlement |
The table settles the immediate question, but the consequence shows up in operations. Confusing txid with EndToEndId makes a team ask its institution for the wrong field during a dispute and lose days. Confusing MED with a chargeback makes a company answer a Pix refund claim as though it were a card dispute, and miss the window it had to defend itself.
Putting this vocabulary to work
Three steps a company can take without hiring anyone.
- Replace static QR codes with identified charges wherever there is volume. Every charge issued with txid filled in comes back linked to its order. The gain is not technical, it is human: the reconciliation team stops deducing the origin of identical payments and handles only the exceptions.
- Write the MED procedure before the first claim arrives. Who opens the notice, within how long, which sale documents are kept and who signs the contest. The window runs from the refund, and an operation with no defined procedure discovers that with the clock already running.
- Review limits and certificates on the same calendar. An insufficient limit and an expired certificate take a payment down in the same way, and both are predictable. A quarterly check settles it and avoids the discovery on the day of the large payment.
Frequently asked questions about Pix terms
What does MED mean in Pix?
MED stands for Mecanismo Especial de Devolução, the special refund mechanism. It is a set of Central Bank rules, in force since November 2021, allowing a refund request on a Pix in cases of fraud, scam or operational failure. The institutions involved analyse the claim, block available balance and decide on the refund.
What is the difference between txid and EndToEndId?
txid identifies the charge and is set by whoever issues it, usually carrying the order or invoice number. EndToEndId identifies the transaction and is assigned by the payer’s institution, travelling with the payment between institutions. In a dispute, EndToEndId is the field that traces; txid is the one that explains the origin.
What is a Pix key and how many can a company hold?
A Pix key is a nickname identifying an account in place of bank, branch and number. It can be a CNPJ, an email address, a phone number or a random string. An account can hold more than one key, within the regulation’s cap, and each key belongs to a single account at a time, portable to another institution.
Can a foreign company receive payments by Pix?
Pix settles inside Brazil, between accounts at Brazilian institutions, and does not cross borders. A foreign company receives through a Brazilian entity and account, or through a payment partner holding one. Paying a Brazilian supplier “by Pix key” means paying a Brazilian account after the foreign exchange step, not sending an international wire.
Can a Pix be cancelled or reversed?
Not the way a card payment is reversed. The transaction is final once settled. Funds return only through a new operation: a refund issued voluntarily by the recipient, or a refund decided through an MED claim where there was fraud or operational failure.
Is automatic Pix the same as direct debit?
No. Direct debit depends on a bilateral agreement between the company and each customer’s bank. Automatic Pix runs on Pix infrastructure, available since June 2025, with a single authorisation given by the customer and reach across every participating institution, with no bilateral agreement required.
Why this vocabulary stopped being a technical matter
Terms like txid, precautionary block and automatic Pix authorisation were born in integration documentation. They left it because Pix stopped being a transfer channel and became the infrastructure a Brazilian company bills, collects, pays and disputes on.
Our reading is that understanding these terms is now part of the job of whoever runs the cash. When a contest window changes, when recurring billing stops depending on bank agreements and when reconciliation comes to rest on one field filled at issuance, decisions about cash, collection and risk start to depend on reading the term correctly. Trio positions itself as the new generation of corporate account, and part of that role is explaining the infrastructure rather than only operating it.
Two routes from here, depending on your territory: How automatic Pix can transform receivables management if the subject is recurring collection, and How MED works if the subject is refunds and risk. To talk through how your operation receives money today, talk to Trio.