Accounts for a group with multiple CNPJs: what to compare before choosing
Pooling cash across CNPJs does not save time. It creates corporate, regulatory and tax risk. The criterion that decides the account is traceability per entity.

TL;DR: A group with multiple CNPJs does not need a single account. It needs one account per CNPJ plus a management layer on top. Pooled cash feeds commingling claims, runs into Resolution BCB 518, and weakens the documentary evidence that separates an intercompany current account from a loan subject to IOF. Compare six criteria before choosing. The decisive one is traceability per CNPJ.
Every group reaches the same point. The corporate structure grows for sound reasons, risk segregation, tax regime, a different partner in each vehicle, and the banking architecture does not keep up. On closing day, choosing an account for a group with multiple CNPJs stops being a treasury topic and becomes a compliance topic.
A CNPJ is the tax ID of a single legal entity. A group that holds twelve of them holds twelve sets of books, twelve filing obligations and, in practice, twelve bank logins.
The money already moves in real time. The traceability does not.
In October 2026, business to business transfers accounted for 51.8% of all value settled through Pix, Brazil’s instant payment system, against 35.1% in October 2021, according to the Pix statistics Trio compiles from Central Bank data. In the same month, per the same Central Bank series, R$ 1.28 trillion, or 39.1% of total value, was pure treasury movement: transfers between accounts held by the same owner.
That last figure is the problem in one number. A group moves money between its own entities constantly, and that is exactly where the wrong account charges its price.
What follows does not compare fees. It compares architecture.
What is an account for a group with multiple CNPJs?
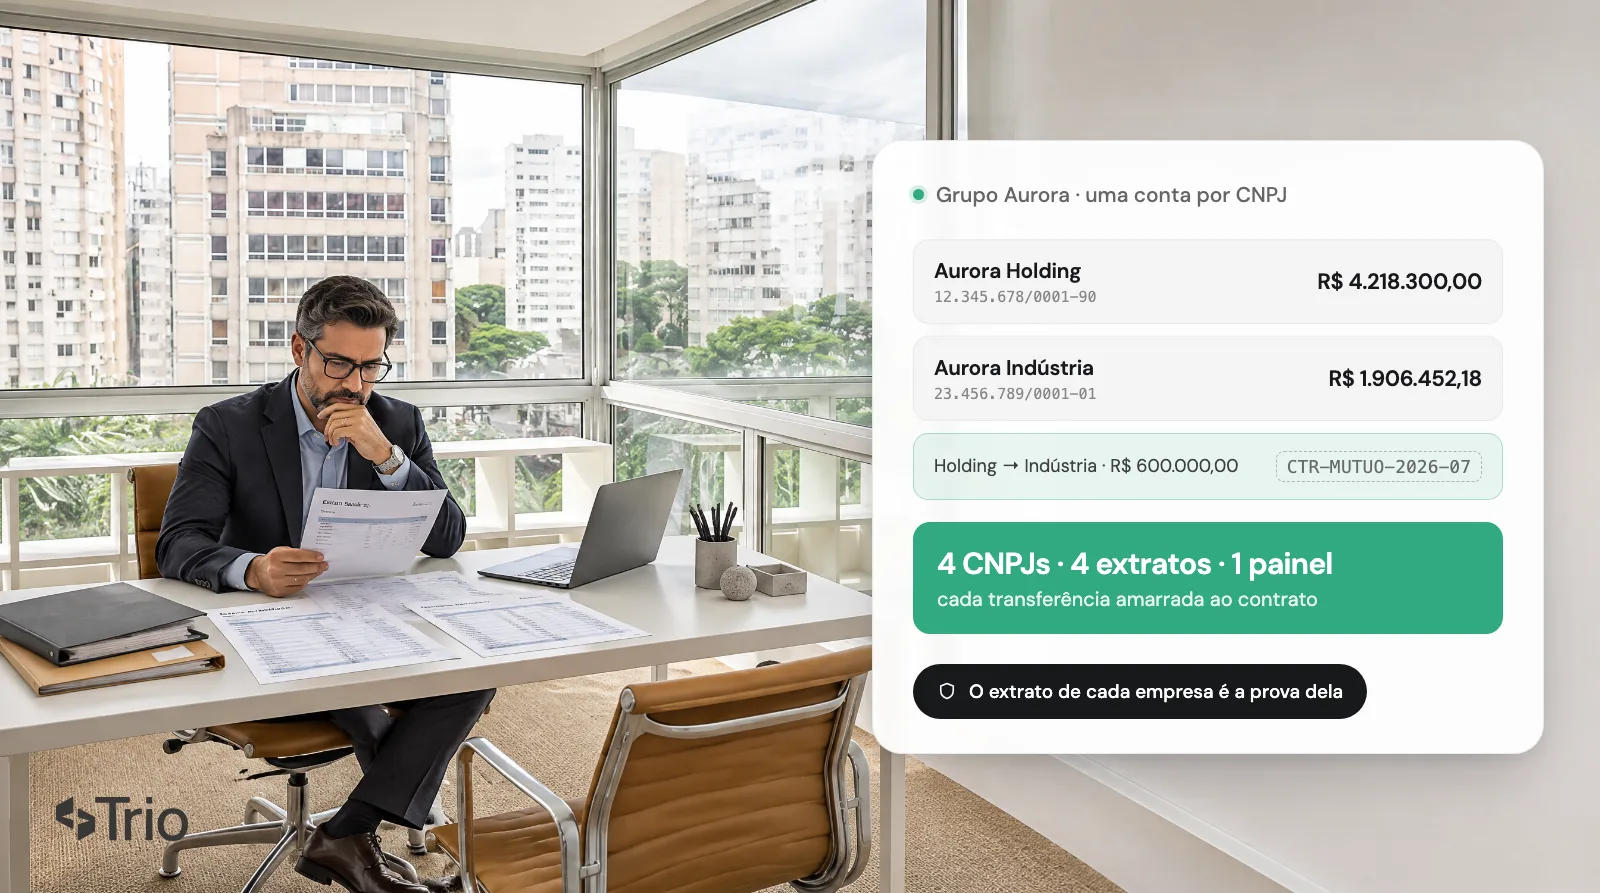
It is not an account shared between the entities. It is an arrangement in which each CNPJ keeps its own ownership, statement and ledger, while approval rules, balance visibility and integration are concentrated in a single control point.
What gets consolidated is the management layer. Never the cash.
The distinction holds for any design: a holding company with operating subsidiaries, a head office with branches, project SPVs or a franchise network. In all of them the operational question is the same, and it has nothing to do with how many accounts exist. It has to do with how many places you must visit to close the month.
A corporate account designed for groups solves this without forcing you to choose between corporate segregation and consolidated visibility.
Why does a single account across CNPJs cost more than it looks?
Because it transfers a cost to the group that never shows up in the fee schedule: legal risk and tax risk. Pooled cash across separate legal entities supports a commingling claim under the Civil Code, falls under Resolution BCB 518, and destroys the documentary evidence you will need if assessed.
Start with the corporate side. The existence of a corporate group, on its own, does not create joint liability, and isolated indicators are not enough to treat several CNPJs as a single organism.
Practice is what creates it. One entity paying another’s bills, and a common cash pool, are the signals courts read as a de facto group. The Santa Catarina State Court found commingling and upheld enforcement against the companies and their partners in a case with that profile.
On the regulatory side, the window has closed. Resolution BCB 518, issued in November 2025, made it mandatory to close contas bolsão, accounts held in one company’s name but used to move third party funds, from 1 December 2025. Institutions must now maintain their own identification criteria, approved by the board, with ten years of document retention.
In short: a structure that used to be merely untidy is now, for the institution, a supervisory liability.
Intercompany: do tax authorities see a current account or a loan in your statement?
A transfer between group entities can be characterised two ways. An intercompany current account, with reciprocal entries and a balance struck at period end, or a loan, with a clear asymmetry between creditor and debtor. The first tends to keep IOF, the tax on financial transactions, out. The second pulls it in.
This is the section that justifies the whole article, and almost no account comparison touches it.
CARF, the federal administrative tax court, is split. One ruling holds that IOF does not apply to a mere financial flow between entities of the same group. A 2026 decision went the other way and upheld the charge on loan operations between affiliates where documentary proof of purpose was missing.
The criterion separating the two outcomes is known: reciprocal entries and the purpose of striking a balance, against the asymmetry typical of lending. The same reasoning shows up in the treatment of advances for future capital increase, where delay in capitalising tends to recharacterise the advance as a loan.
Notice where this lands. None of these disputes is won on argument. They are won on records.
Records, in practice, means a statement per CNPJ with an identifier tying each movement to the contract and to the matching accounting entry. If group treasury runs through a single account and the split happens afterwards in a spreadsheet, you do not have records. You have reconstruction.
The same applies to cost sharing. Brazilian tax authorities treat amounts received by the centralising entity as reimbursement rather than revenue, provided the agreement itemises what is allocated to each legal entity in the group, with expenses that are necessary and evidenced. CARF, however, has ruled the other way on shared services, which raises the weight of documentation.
In a corporate group, an account is not only a payment instrument. It produces evidence.
The six comparison criteria
With the risk mapped, selection becomes objective. For each criterion, the question that should go into the proposal.
1. Onboarding the next CNPJ. Groups incorporate entities. If each addition reopens full KYC from scratch, the cost sits in the calendar, not in the fee. Ask: how long from request to a new CNPJ of the same group transacting?
2. Statement per CNPJ and consolidated balance. Both at once, with no export step. Ask: can I start from consolidated cash and drill down to an individual transaction without switching logins?
3. Approval rules per entity. An approval matrix combining CNPJ, amount and operation type. Ask: can I set different approvers in each entity within the same access?
4. Integration and traceability. API, webhook and an identifier per transaction. Without it, the point above about records does not hold. Ask: does the identifier travel to the statement and come back in the return file?
5. Regulatory model. Where the balance is held and under which legal protection. Ask: is the authorisation published by the Central Bank, and are funds held as segregated assets?
6. Cost of a dormant account. Groups carry inactive CNPJs. A fixed monthly fee multiplied by fifteen accounts becomes a real line item. Ask: what does it cost to maintain an account with no movement?
For larger groups, criteria 3 and 4 usually decide on their own.
How should approval rules work across multiple CNPJs?
In a group, approval operates on two axes at once: by entity and by amount. The director of an operating company approves within it, not in the holding company. Add a third profile, read only, so accounting, audit and the board can follow without the power to move money.
The market still fails at this structurally. The Open Finance consent journey was designed for a single user, which blocks companies with joint management. An EY study finds that requiring multiple authorisations hurts corporate adoption.
The numbers show it: only 574,000 of 79 million consents come from legal entities.
Require a proof of concept before signing. Two CNPJs, three profiles, one payment that needs dual approval.
Reconciliation at multi-CNPJ scale
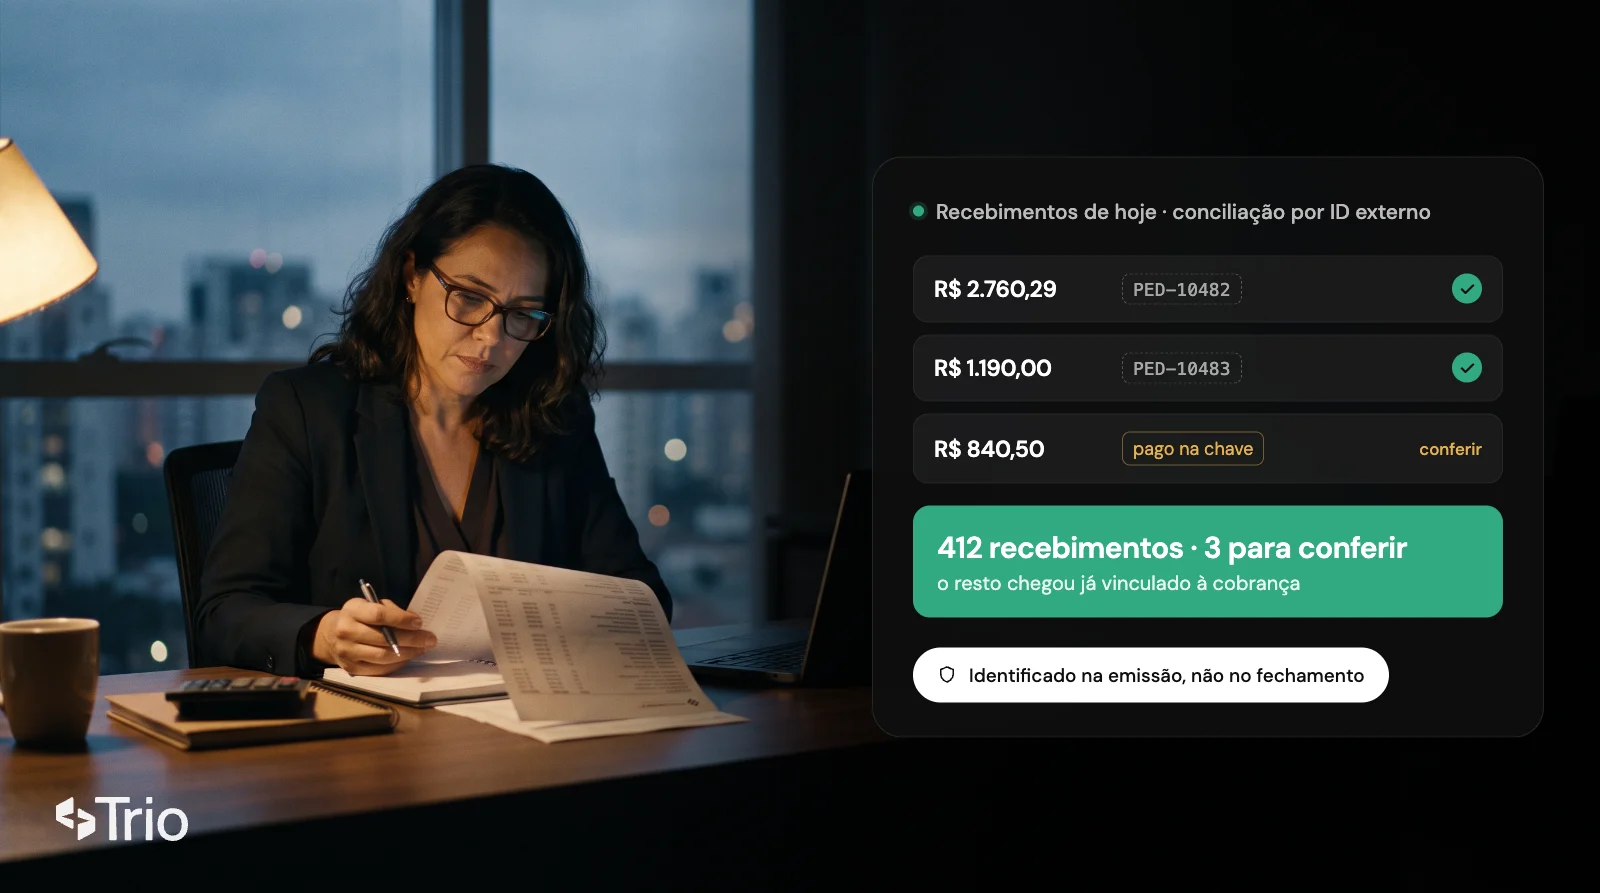
This is where the sales promise meets the close. Manual processes remain the main obstacle to closing for 69% of finance leaders, according to The Hackett Group.
Three capabilities handle most of the volume:
- An identifier at settlement. The transaction identifier is what enables automatic matching by cost centre and by CNPJ.
- Structured returns. A file or webhook the ERP consumes, not a PDF someone retypes.
- Bulk execution. Suppliers across multiple CNPJs go out in batch payments, with one approval and item level returns.
The honest test is not peak volume. It is the month with a discrepancy: how long it takes to locate an intercompany movement from six months ago and tie it back to the contract.
Bank or payment institution: what changes for group treasury?
A payment institution is authorised by the Central Bank of Brazil to offer accounts and payment services without lending out deposited funds. The balance sits in segregated assets, beyond the reach of the institution’s creditors. In exchange, there is no deposit insurance from the FGC, Brazil’s deposit guarantee fund.
Article 12-C of Law 12,865 of 2013 is explicit: the funds do not mix with the institution’s assets and do not answer for its obligations. These are different protection regimes, and treating one as simply superior is an oversimplification.
For group treasury, the decision rarely turns on that axis. It turns on criteria 1, 3 and 4. Whoever delivers CNPJ onboarding in days, an approval matrix per entity and an API with an end to end identifier tends to win, regardless of the licence.
Confirm the authorisation on the Central Bank site before any proposal.
The horizon: split payment and the alphanumeric CNPJ
Contracting an account today means contracting for 2028.
Split payment, which withholds tax at settlement and pays the supplier the net amount, will be tested on business to business operations in 2027 and becomes mandatory in 2028. Intragroup operations are B2B, so they fall in the first phase. The postponement does not neutralise the effect on working capital, systems and commercial relationships. For depth, review the split payment mandate.
In parallel, the first alphanumeric CNPJ was issued on 31 July 2026, and the tax authority confirms that both formats remain valid across all processes. A group that incorporates entities often needs to know whether its partner already handles the new format in registration, validation and return files.
What to take away
The choice comes down to three decisions.
Keep one account per CNPJ and consolidate only the management layer. Corporate segregation without financial segregation is risk taken on with nothing in return.
Treat traceability as a tax requirement, not a convenience. In any dispute over intercompany flows, cost sharing or de facto group status, the statement per CNPJ with an identifier is the asset you will want to hold.
And contract with 2028 in view, with split payment and the alphanumeric CNPJ already scheduled.
Trio is a payment institution authorised by the Central Bank of Brazil, with its own infrastructure and a direct connection to the financial system, built for groups with multiple CNPJs. Talk to Trio and review the architecture against your group’s entities.
Frequently asked questions
Can I centralise cash from every entity in the group into one account?
Not advisable. Beyond supporting a commingling claim under article 50 of the Brazilian Civil Code, the practice lost regulatory ground with Resolution BCB 518, in force since December 2025, which requires closing pooled accounts used to move third party funds. There is also an evidentiary cost: without a statement per CNPJ, proving the nature of each intercompany transfer becomes difficult.
Does a transfer between entities of the same group trigger IOF?
It depends on how the operation is characterised, and administrative case law is split. CARF has issued rulings keeping IOF out of a mere financial flow in an intercompany current account with reciprocal entries, and 2026 decisions upholding the charge where the operation was characterised as a loan without documentary proof. Evidence of the nature of the flow is the deciding factor.
How many accounts should a corporate group keep?
At least one per active CNPJ, given the requirement for separate books and statements. What gets unified is management: single access, consolidated balance, an approval matrix per entity and API integration. Consolidating cash is not the same as consolidating visibility.
Is a payment account suitable for a group’s cash?
Article 12-C of Law 12,865 establishes that funds in a payment account constitute segregated assets that do not mix with the institution’s property and do not answer for its debts. The relevant difference against a bank deposit is the absence of FGC deposit insurance. Authorisation should be verified on the Central Bank website.
What does split payment change for intragroup operations?
The mechanism withholds tax at settlement, so the supplier receives only the net amount. It will be tested on business to business operations in 2027 and becomes mandatory in 2028. Since intragroup transactions are B2B, groups are affected in the first phase, with direct impact on working capital and cash forecasting.