Pix receivables management: how to close the month without checking payment by payment
Half of all Pix payments arrive with no charge attached. The problem is not volume, it is the identifier, and it is solved at issuance, not at month-end close.

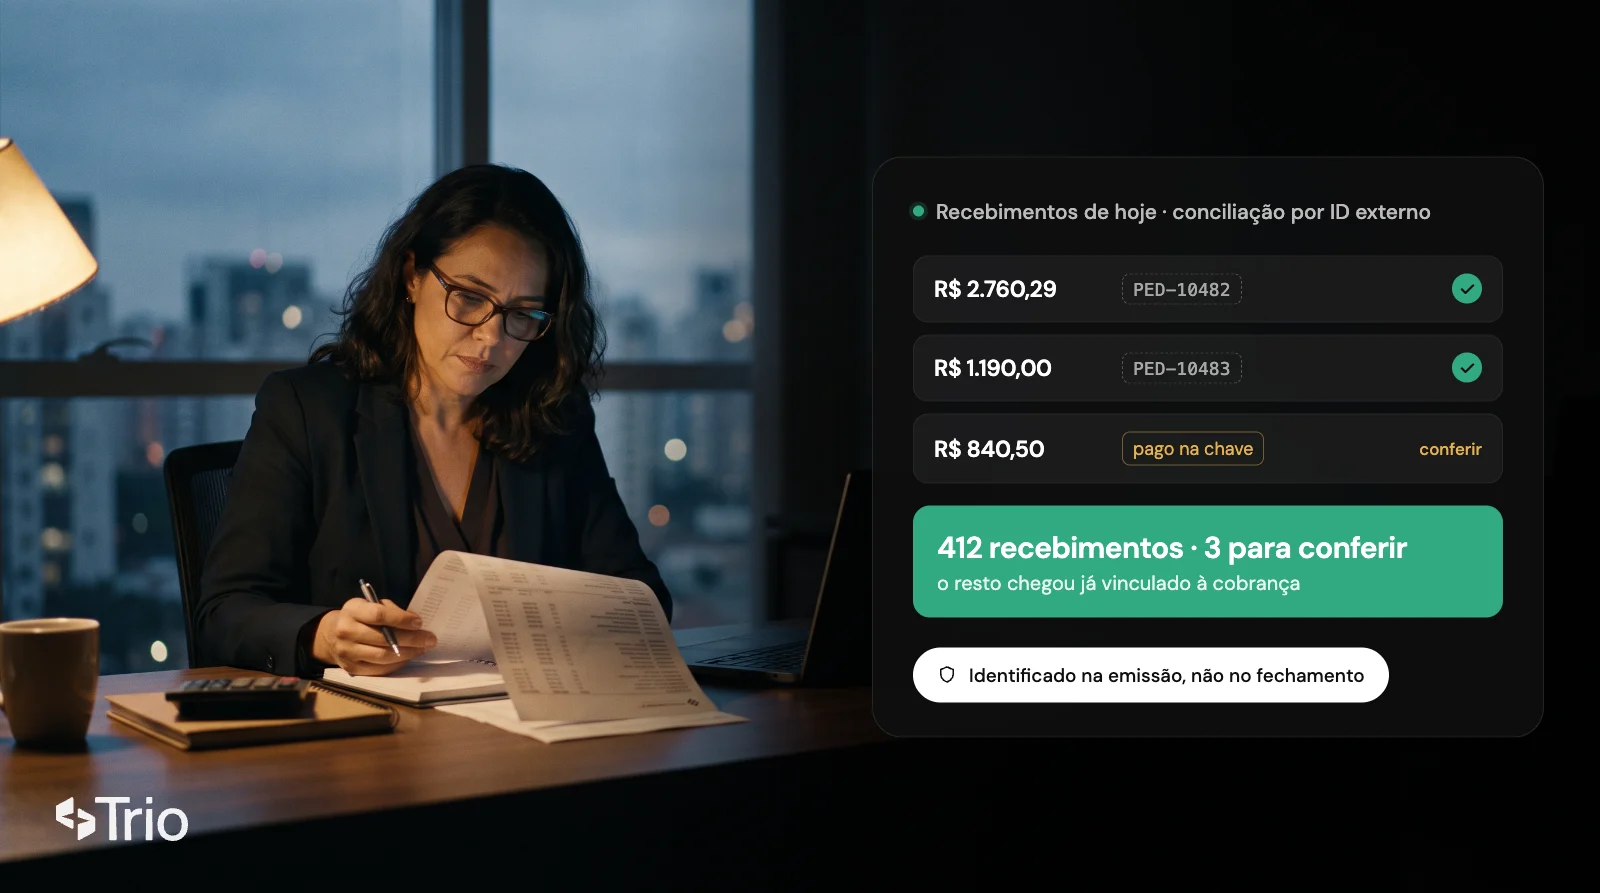
Pix receivables management is the set of practices that links every payment received to the charge that originated it, without manual work. The problem is solved before the payment, not after. When a charge is issued already carrying a unique identifier, the Pix arrives tied to the order, the contract or the invoice, and closing the month stops being a matching exercise.
It is 2:32 p.m. on a Tuesday. Since the business day opened, 412 Pix payments have landed in the company account. The bank statement shows payer name, amount and timestamp. The sales system shows 1,890 open charges. The two lists share no common field.
So begins the work nobody budgeted for: searching the system for a charge of R$ 2,760.29 under a name resembling “Lumen Store”, hoping there are not two. Whatever finds no match becomes a pending item. Whatever becomes pending delays the write-off. Whatever delays the write-off comes back as a duplicate charge sent to someone who already paid.
The common reading is that this is a volume problem, solved by hiring another person or building a better spreadsheet. It is not. It is an identifier problem, and that is why it can only be solved at the moment the charge is created.
What Pix receivables management actually means
Pix receivables management means ensuring that every amount entering the account can be attributed, without human intervention, to the charge that generated it. It is not balance monitoring, and it is not an inflow report.
The confusion exists because Pix brilliantly solved settlement and did not, on its own, solve attribution. The money arrives in seconds, 24 hours a day, weekends and holidays included. But arriving fast and arriving identified are two different things, and the second depends on a decision the company makes before invoicing.
A collections operation with four people in finance can reconcile a few hundred payments a day by hand. Past that point, the choice is no longer between reconciling faster or slower. It becomes a choice between reconciling and not reconciling.
The practical consequence shows up in cash. While a payment is unattributed, it exists on the bank statement and does not exist in the management system. The company has the money and does not have the information, and it is the information that releases the goods, closes the contract and stops the dunning sequence.
Nearly half of all Pix payments arrive with no charge attached
According to Brazilian Central Bank open data for September 2026, 38.1% of Pix transactions settled in the SPI were initiated by Pix key and 9.3% by manual entry of bank details. Together, the two methods account for 47.4% of the total.
These two paths share one trait: neither originates from a charge. The payer picks the recipient, types an amount and sends. On the receiving side, a credit arrives with a name and an amount, carrying nothing that ties it to a specific order.
In the same month, dynamic QR Code accounted for 44.1% of transactions. That is the opposite path: a dynamic QR Code is generated for one specific charge and carries an identifier of its own. Static QR Code, at 8.3%, is reusable by design, and therefore tends to repeat the same identifier across different payments.
The arithmetic is uncomfortable and worth spelling out. In a month when the SPI, the system that settles Pix, processed R$ 3.23 trillion across 7.17 billion transactions, according to Central Bank data for September 2026, close to half of all payments reached the recipient with no link to any charge. That proportion is our own calculation over the Central Bank figures.
Business-to-business collection is low volume and high value
A company receiving Pix deals with two populations of payment that barely resemble each other, and treating both the same way is what breaks reconciliation.
In Central Bank data for September 2026, payments from individuals to businesses represented 46.5% of the transaction count settled in the SPI and only 11.5% of the value, with an average ticket of R$ 111. Payments between businesses were 4.3% of the count and 52.1% of the value, with an average ticket of R$ 5,450. The proportions and tickets are our own calculation over Central Bank open data.
Adding both natures together, businesses receiving payment account for 50.8% of transactions and 63.5% of the value that moved through the SPI that month.
The practical reading is this. Consumer collection is a scale problem: thousands of small amounts, impossible to check one by one as a matter of arithmetic. Business-to-business collection is a consequence problem: few payments, but a single unidentified one can hold up the release of a five-figure contract.
A regional distributor receiving 60 payments from retailers per day does not have a volume problem. It has a problem when three of them arrive as aggregated amounts covering several invoices and nobody knows which invoices were settled.
Where reconciliation actually breaks
Reconciliation breaks at one specific point: when the identifier the payment carries is not the same identifier the company system uses.
Three identifiers are in play, and confusing them is the origin of most pending items.
The txid identifies the charge, from the perspective of whoever will receive. The EndToEndId identifies the transaction that was actually settled. The company system identifier, the order or invoice number, identifies the commercial obligation that motivated the whole thing.
These are three distinct questions: what was charged, what was paid and what was sold. Reconciliation is only automatic when all three are tied together from issuance. When a company issues a charge without carrying its own order number into it, it is asking someone, later, to guess the link from a name and an amount.
The Pix Initiation Standards Manual, published by the Brazilian Central Bank, describes the txid as the transaction identifier from the receiving user’s perspective, generated at the moment the charge is created precisely to identify it uniquely. Using the field for reconciliation is not a creative workaround. It is the purpose the field exists for.
One limit deserves acknowledgment. No identifier solves the payment a customer makes outside the process, by Pix key, ignoring the charge that was sent. That case will keep happening, and the realistic goal is not to eliminate it but to reduce it to an exception one person can handle.
What changes when the charge is born with an identifier
When a charge is created already carrying the number the company system uses, the payment comes back with that number, and the write-off stops depending on someone comparing lists.
The change is one of sequence, not of tooling. The same team, the same ERP and the same volume produce different outcomes depending on whether the identifier enters the charge at the start or gets hunted for at the end.
In practice, three things move. Attribution shifts from month-end close to the moment of credit. Discrepancies surface the day they happen, not thirty days later. And the dunning sequence stops firing at people who already paid, because the system knows they paid.
A services marketplace processing 400 payouts a day needed two people and half a morning to close reconciliation. The bottleneck was never volume. It was the absence of a common field between the order system and the bank statement.
This is where the market term deserves pairing with the product term: reconciliation by identifier, which on the Trio platform appears as external ID, is the field that travels from charge issuance to the credit in the account. The principle is the same at any provider offering the feature, and the question that matters when contracting is whether the identifier crosses the entire path or stops halfway.
Pix collection methods and the identification each one delivers
Not every way of receiving Pix delivers the same degree of identification, and picking the wrong method for the use case is what creates manual work later.
| Collection method | Originates from a charge | Identifier per payment | When it makes sense |
|---|---|---|---|
| Published Pix key | No | None | Occasional, low-volume collection |
| Static QR Code | No | Reused | Physical point of sale, variable amount |
| Dynamic QR Code | Yes | Unique per charge | Order, invoice or contract collection |
| Pix Cobrança with due date | Yes | Unique, with interest and penalty rules | Subscriptions, invoices with terms |
| Pix Automático | Yes | Unique per cycle | Recurrence authorized once |
| Payment link | Yes | Unique per charge | Sales through non-integrated channels |
The table explains why the answer to “how do I organize Pix collection” is almost never “publicize the key better”. The key is the easiest path to implement and the only one that produces no reconciliation information at all.
On Pix Automático, which handles recurrence, expectations still deserve calibration. In September 2026 it accounted for 8.9 million transactions in the month, according to Central Bank data, representing 0.13% of the total settled in the SPI. It is a useful and growing instrument, not a general replacement for recurring invoicing.
The most common mistake is not technical, it is sequential
The mistake that generates the most rework is not in the choice of tool. It is in the order of decisions: the company chooses how it will collect before deciding how it will reconcile.
It goes like this. Someone needs to get paid fast, publishes the Pix key, and it works. Volume grows, payments keep arriving unidentified, and the response is to hire another person to check. By the time reconciliation finally reaches the agenda, there is already a customer base trained to pay the way that identifies nothing.
Reversing that later costs more than getting it right at the start, because it involves changing the behavior of the people paying, not just the system of the company receiving.
A subscription operation with 2,300 active customers learned this while migrating from Pix key to identified charges. The technical work took two weeks. Getting the entire base to stop paying to the old key took seven months.
The question that prevents the problem is simple and belongs before the choice of payment method: when this money lands in the account, what exactly will say which sale it belongs to?
Five steps to organize Pix collection
- Measure your unidentified payment rate. Take one closed month, count how many credits needed human intervention to become a write-off, and divide by the total. Without that number, any improvement is perception.
- Separate the collection key by purpose. A key tied to the operating entity’s tax ID, used only for commercial collection, already separates sales from transfers between your own accounts.
- Make every new charge carry your system identifier. Order, contract or invoice number, inserted at issuance, not afterward. This is the step that changes the outcome.
- Treat payment outside the charge as a monitored exception. Define who watches it, how often, and the maximum time to resolve. An exception without an owner becomes a permanent pending item.
- Measure the close by time, not by feel. How many business days after month-end is reconciliation complete? That single number is the best indicator of the health of your receivables.
Frequently asked questions
Can you reconcile Pix payments without an identifier?
Yes, by manually matching name, amount and date, and it works up to a few hundred payments a month. Beyond that, errors grow faster than volume, because repeated amounts and similar names start colliding frequently. The method does not scale, but it is legitimate while the operation is small.
What is the difference between txid and EndToEndId?
The txid identifies the charge created by the party that will receive, and serves to link the payment to the order. The EndToEndId identifies the Pix transaction actually settled and travels with the receipt. One charge can receive more than one payment, in which case there is one txid and several EndToEndId values.
Does Pix cost money for businesses?
Yes, in most cases. Unlike Pix between individuals, collection by a legal entity can be charged for, and the model varies between a percentage of the amount, a flat fee per transaction, and bundles with an included allowance. The cost depends on the contract with the institution, not on a single market rule.
Does the customer have to do anything different for the payment to arrive identified?
No, provided they pay through the charge they received. When scanning a dynamic QR Code or using the link sent to them, the identifier travels along with no extra action. Payments stop being identified when the customer ignores the charge and pays straight to the key.
Does receiving by Pix change any tax obligation for the company?
No. The payment method does not change tax rates, does not create a new ancillary obligation, and does not replace invoice issuance. What changes is the quality of the trail: an identified payment makes it easier to demonstrate the match between a sale and a cash inflow. Compliance remains the company’s responsibility.
How long does automatic reconciliation take to implement?
The technical work usually takes two to six weeks, depending on ERP integration. The real timeline is set by another variable: how long the customer base takes to migrate from paying to the key to paying through the charge. That second timeline is usually longer.
What this says about where the market is heading
Reconciliation is not a spreadsheet problem. It is an identifier problem, and the identifier is an architecture decision made at charge issuance, not at month-end close.
Pix made settlement instantaneous and all but irrelevant as a competitive differentiator: everybody gets paid fast. What separates a financial operation that scales from one that seizes up has become something else, which is being able to explain every movement to the customer, to accounting and to the auditor, without depending on anyone’s memory.
That layer, not speed, defines the next generation of financial infrastructure for companies. It is also why Trio treats accounts receivable as an identification problem rather than an issuance one: issuing charges at volume is the easy part.
To continue: if your case is recurrence, how Pix Automático can transform receivables management covers that specific instrument. If the question is still vocabulary, Everything about Pix explains the terms used here, from txid to MED. And if you want the full data by transaction nature, it is open at Pix Statistics.